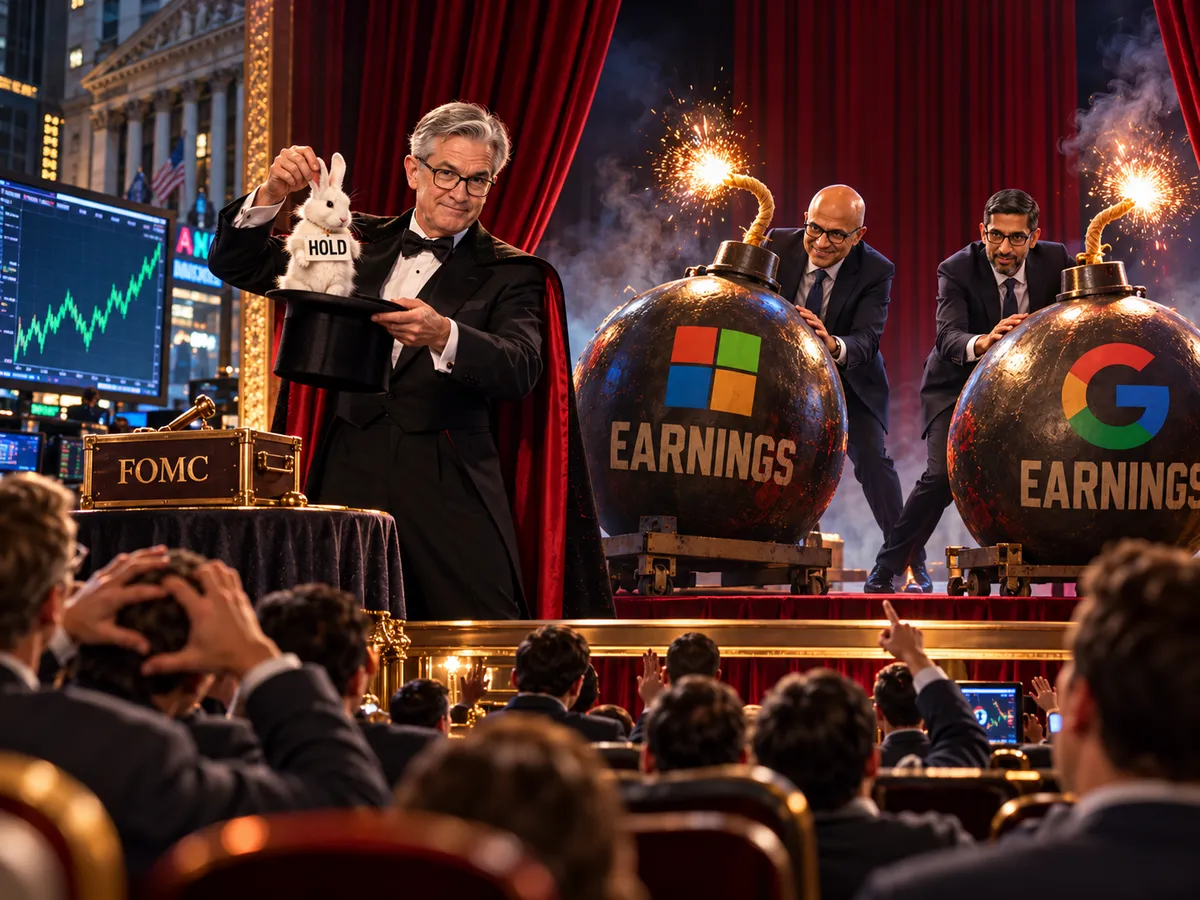
The Fed announces at 2pm ET, it’s the most telegraphed decision of the year, and the market has treated it as settled for weeks. Which makes the FOMC the opening act – the actual verdict on this market gets delivered after the close, when Microsoft and Alphabet report.
The bullish case walking into tonight is real, and it came from memory. SK Hynix, the supplier of the high-bandwidth memory every AI buildout is fighting over, posted operating profit up 7x year over year and flagged capacity constraints. Suppliers don’t do optimism, they do backlog, and this one is telling us the orders exist.
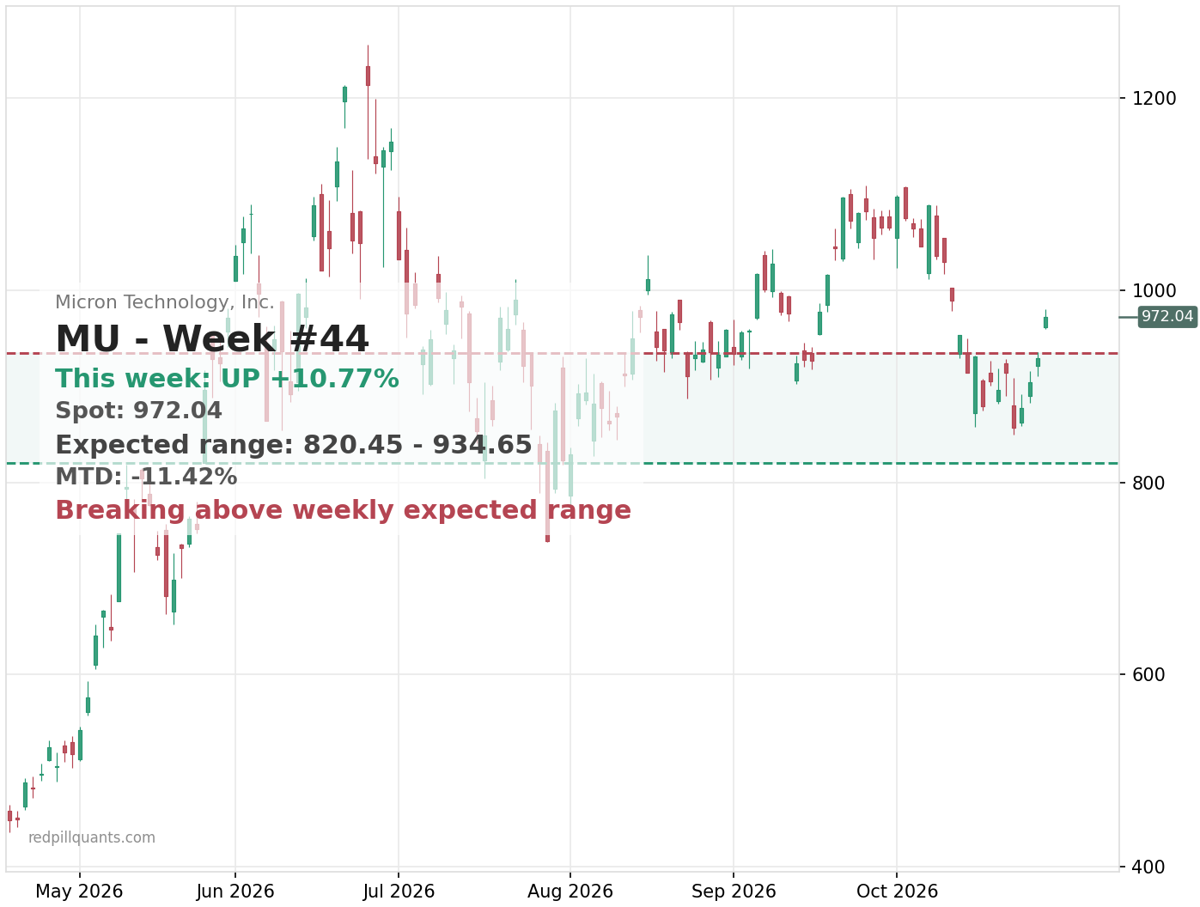 The cleanest expression in the sector is Micron. MU closed near $972, up about 11% this week, and it’s pressing above the upper boundary of its weekly expected move around $935. When a stock closes outside the expected weekly range, that’s repricing, not drift.
The catch: the bigger structure is still an older bearish one under repair. This is a breakout trying to prove itself, not a trend to take to the bank. However, memory demand is real and it’s not going anywhere.
The AI trade’s open question is the output. Whether the hyperscalers writing the capex checks are converting it into revenue anytime soon remains to be seen. That’s what tonight is actually about.
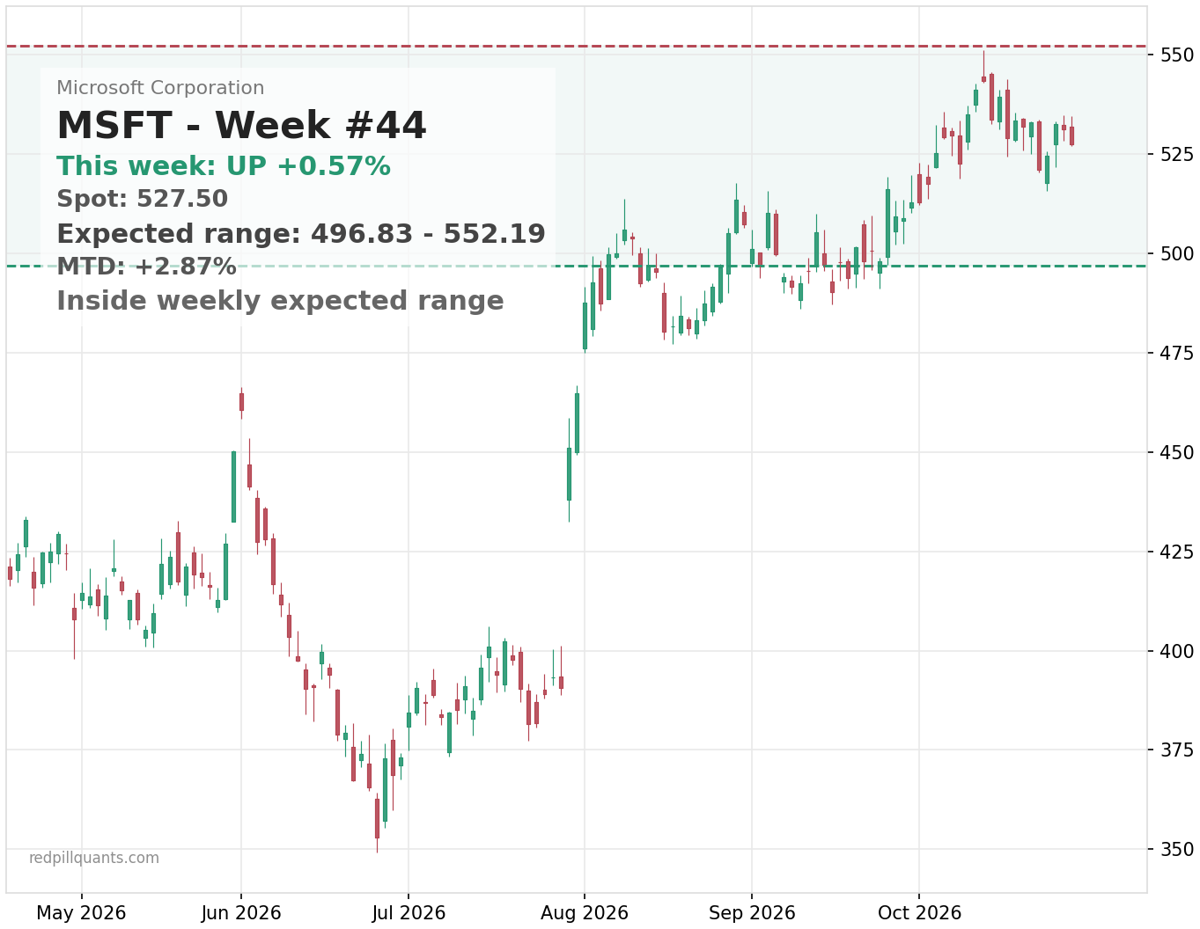 Microsoft enters the room on a high bar, currently trading near $530. It’s sitting pretty in the upper quartile of its three-month range with the uptrend intact, inside a weekly expected move of roughly $497 to $552.
The chart says the market wants to believe, and earnings nights are when reality proves them right or wrong. The trouble is that a lot of that belief is already in the price. A cloud number that merely meets expectations can get sold like a miss, and anyone holding calls through it can be right about the business and still lose money on the trade.
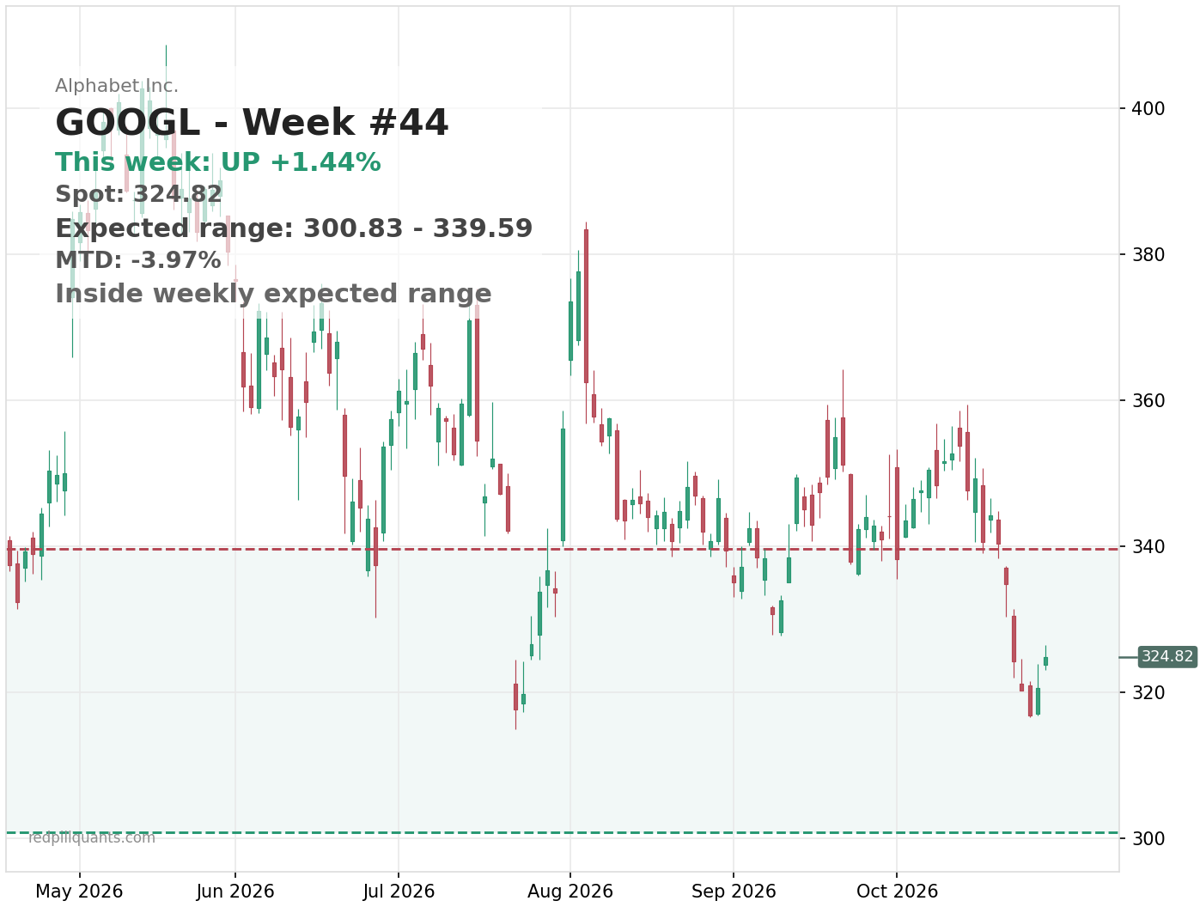 Alphabet is painting the square opposite. GOOGL is near $324, down about 6% over the past month, parked near three-month lows with the structure still in rollover. Downside pressure is favored even though the last few sessions have firmed. Same AI story, completely different chart.
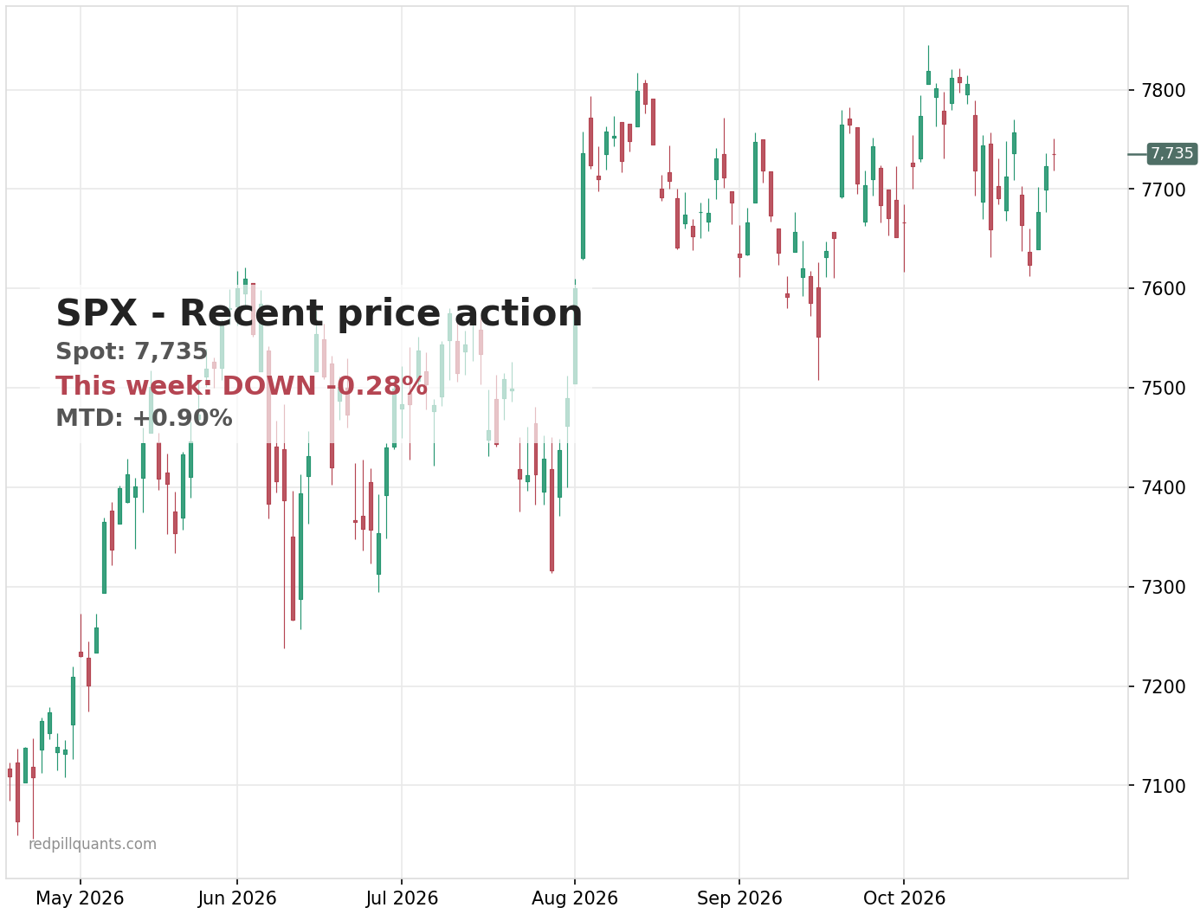
A quick peek at the index explains the mixed mood. SPX is near $7730, at the upper end of its three-month sideways range, with the regime reading range-and-pinning and VIX at 17.5. That’s theta-seller paradise.
Payday Friday, my weekly credit-spread system, has been doing its job in it. The ETN bull put closed at target with about 73% of the credit captured, and INTC came off manually with roughly a third. The new October 30th cycle is live: two bull calls, two bull puts. The systems are positioned for contained tape. Tonight decides whether it holds.
bull call | open | CVX | return -0.81 (-25.00%)
bull call | open | HD | return +0.20 (7.00%)
bull put | closed | ETN | return +3.55 (35.00%)
bull put | closed | INTC | return +0.32 (8.00%)
TOTAL | return +3.26
So the watch list is short. Ignore the hold and listen to what Warsh signals about December. In the reports, skip the capex headline, because the spending is the known part. The number that matters is cloud growth, because Azure and Google Cloud are where AI spending either becomes revenue or becomes a capex black hole. If the conversion shows up, the current calm was justified. If capex rises while the revenue commentary gets blurry, then it’s every man for himself.
This kind of read, regime, structure, expected move, what the options are actually pricing, is what SPY Alpha turns into live signals for equities and index options. If you want the systems behind it, check it out here.
Cheers,
Michael