The cubes closed Friday near $750, within a whisker of its highs. Meanwhile roughly 7 in 10 stocks are trading below their 20- and 50-day averages. Market halitosis at its best but nobody seems to care.
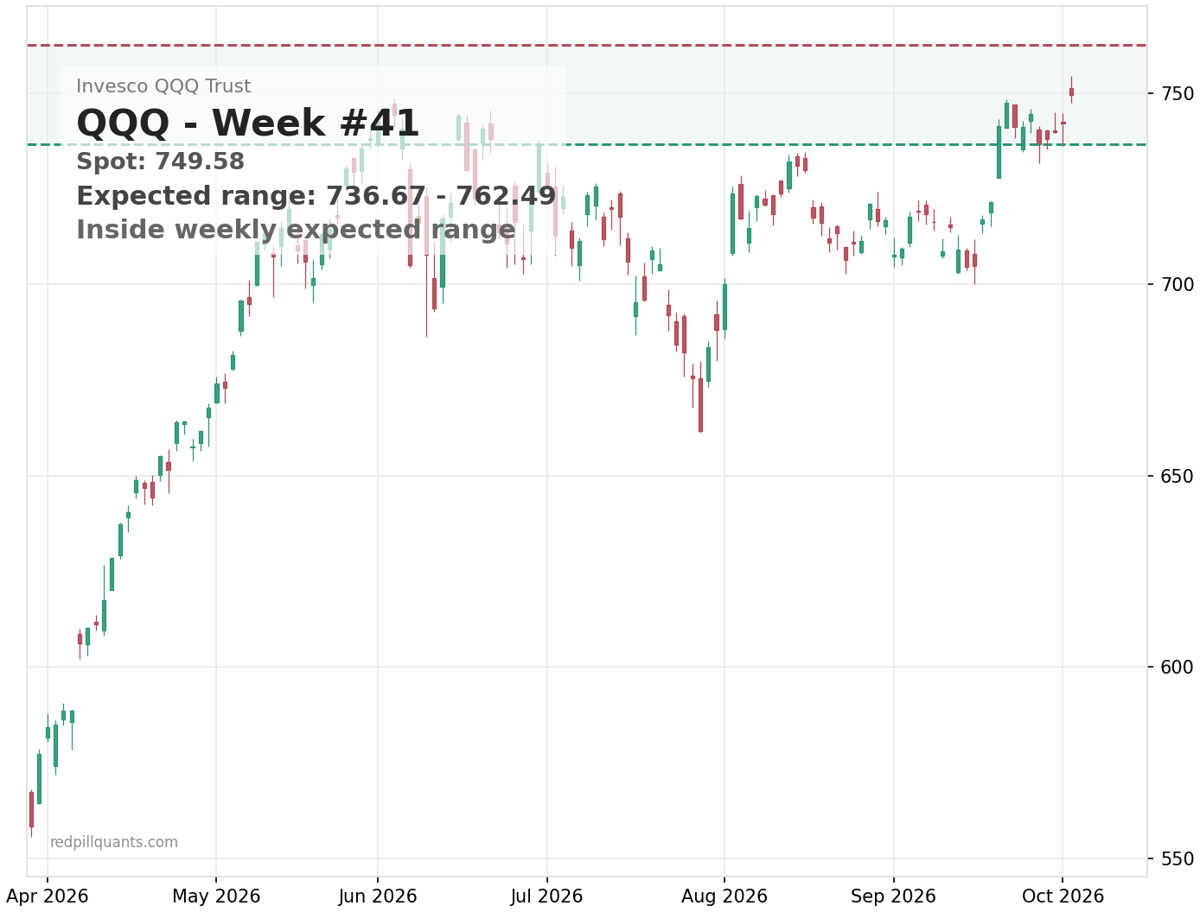
This is what a narrow rally looks like from the inside. The index is cap-weighted, so when a handful of mega-caps do the lifting, QQQ can print records while the median stock goes nowhere. Breadth is just the headcount of who’s actually participating, and right now the headcount is thin.
The lift is coming from the AI complex I’ve kept harping on recently, and that narrative keeps fueling the index. Foxconn just reported Q3 revenue up 47% to about $95B, driven by AI server demand. That supports the hardware side of the trade – servers are clearly being built.
What it doesn’t do is guarantee anything about NVDA’s own numbers. Foxconn for example is a supplier, not a preview. But the market will treat it as a preview anyway, because that’s what markets does with stories they like.
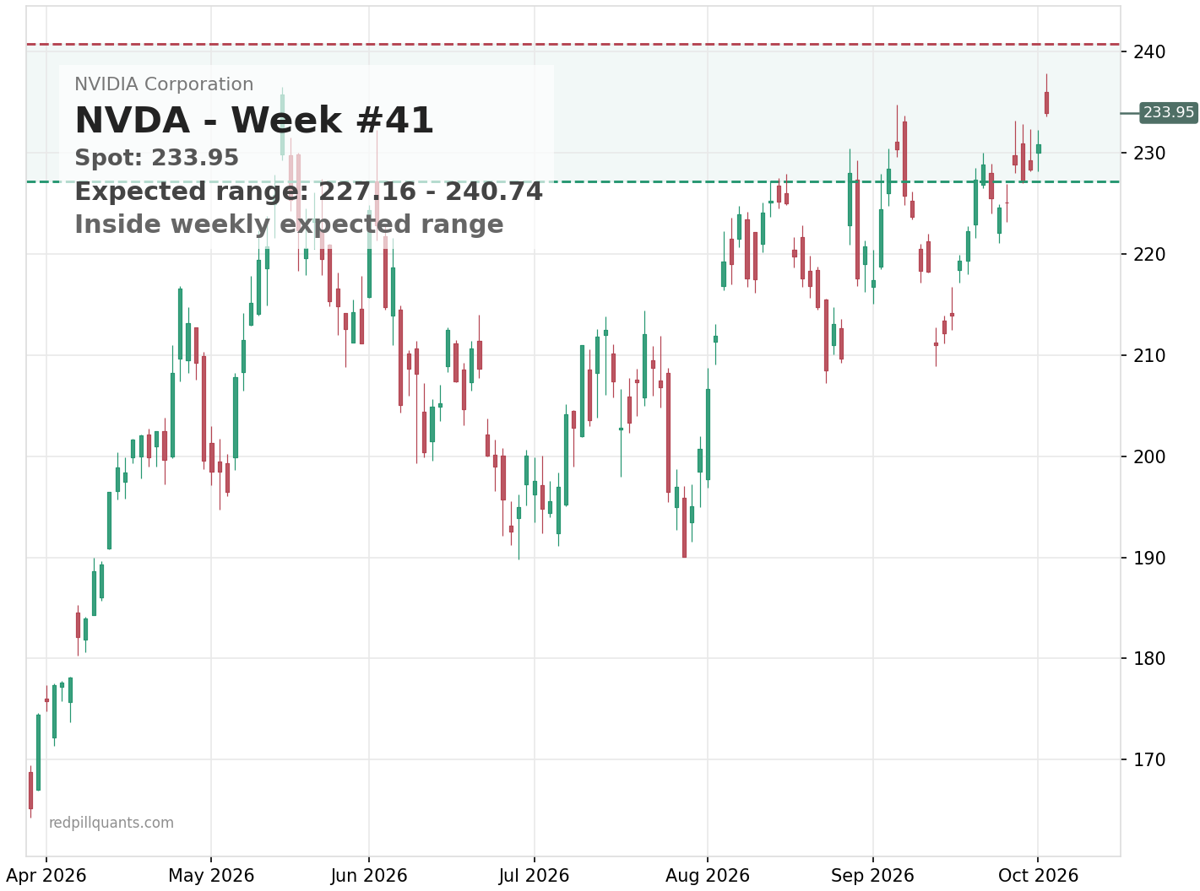
NVDA itself is doing its part – up about 4% on the week, closing near $234, sitting just under its highs. The tape in the leader is firm, and the weekly expected move is narrow, so options are not pricing drama there either.
AMD is the more interesting case. The stock is up roughly 39% over the past 20 days and closed Friday near $634 after another push higher. Cantor Fitzgerald’s read (old school primary dealer) is that the next catalyst is Q4 guidance: if it implies Helios shipments above expectations, the earnings story gets legs.
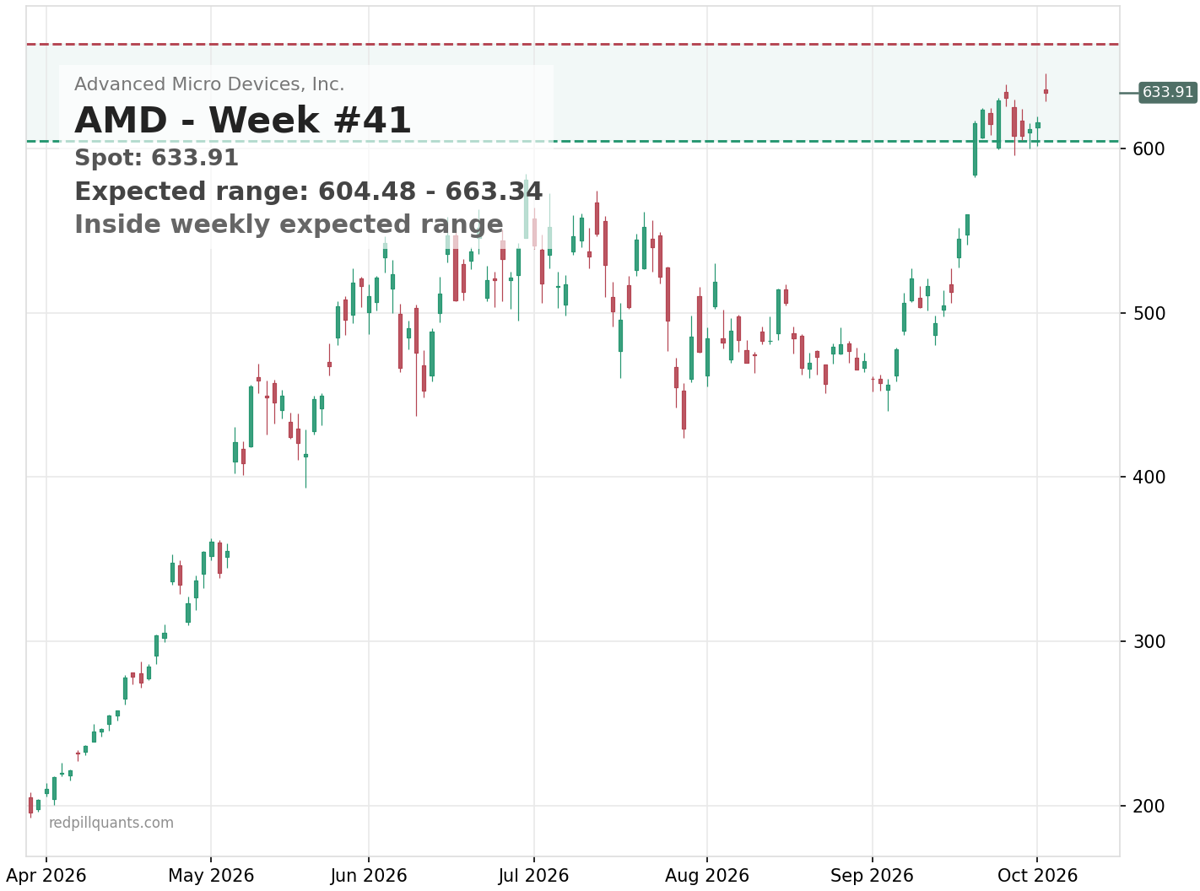
However that’s an analyst framing, not a fact. It’s the right thing to watch, because after a 39% run in a month, the stock has already collected payment for a lot of good news – don’t fall in love with that idea until reality backs it up. Technically speaking, the weekly expected move is about 4.6% – wider than the index, tighter than a frog’s buttocks.
Then there’s META, the cautionary footnote inside the AI theme. Zucker Central describes its recommendation engine as a flywheel – better AI drives engagement, engagement drives ad revenue, ad revenue funds more AI. Elegant. The stock still gave back about 3% this week and sits roughly 7% off its high.
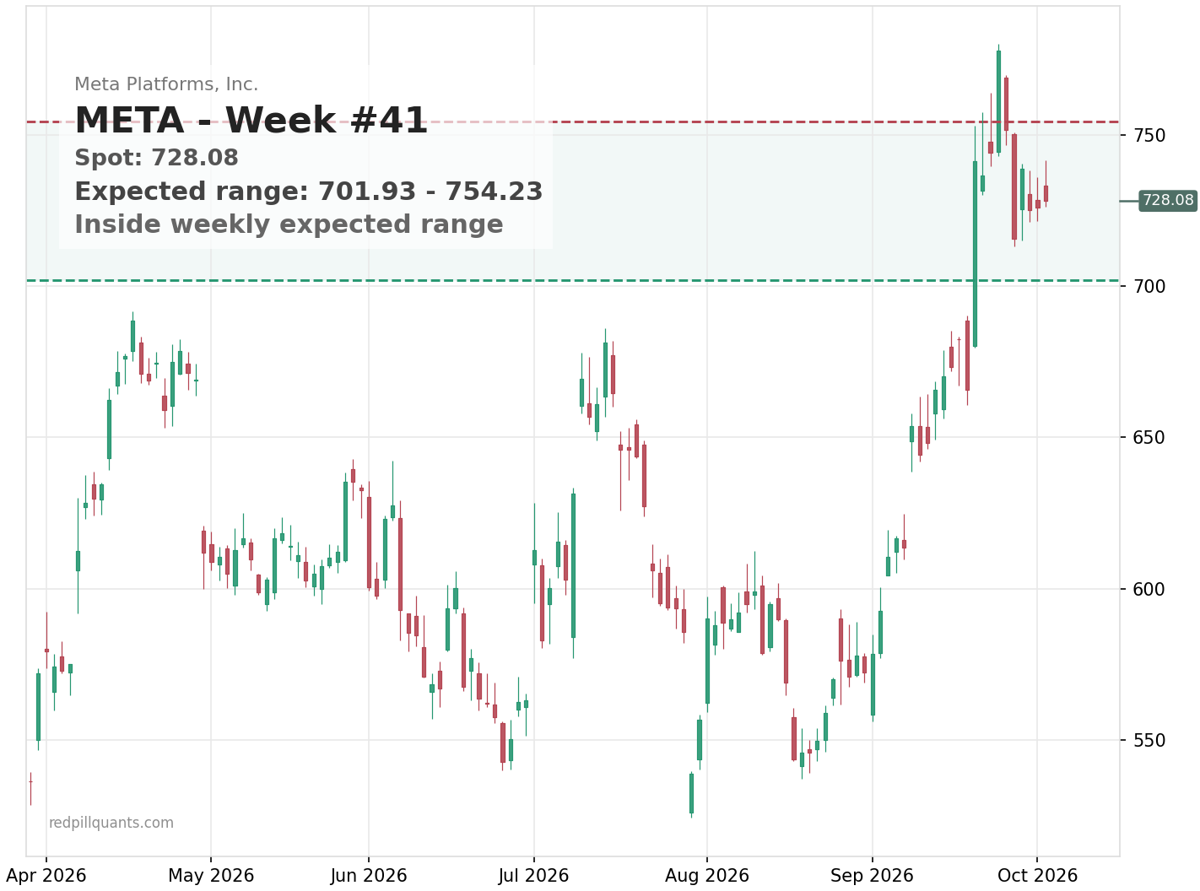
Even inside the winning theme, the market is grading names individually now. That matters, because it tells you the easy phase of this trade – where anything with “AI” in the deck went up together – is not the phase we’re in.
Meanwhile the bond market is not playing along. The 10-year yield is near a 25-year high, which is a genuine headwind for equity valuations, especially the long-duration kind the AI trade is made of. VIX jumped about 5% on Friday to 16, and the weekly expected move on QQQ is a very narrow 1.7% – options are pricing calm at the index level while the internals are split.
So what does this tape do to your setups? Buying QQQ here is buying a handful of tickers in an ETF wrapper – fine if you know that, expensive if you think you’re diversified. And buying laggards because “breadth has to improve eventually” is a thesis, not a setup. The market owes nobody a rotation.
Shorting the leaders because breadth is ugly is the opposite mistake – betting against the only part of the market that’s actually working. Narrow rallies can run longer than seems reasonable, right up until they don’t.
The thing to watch is the bench. If NVDA, AMD, and friends keep carrying, the index can keep floating. If they stall, there is no second string underneath – 7 in 10 stocks are already below their averages. That’s not a prediction. It’s just what the depth chart looks like.
If you want this kind of read – structure, trend state, expected move, what the options market is actually pricing – turned into live signals, that’s what SPY Alpha does for equities and index options. GET ACCESS HERE
Cheers,