Everyone’s attention today is on Samsung, which is expected to report a record tonight: ₩105 trillion, up roughly 763% from a year ago, with the chip division doing the heavy lifting.
Those are pre-earnings estimates, not results, worth remembering before the confetti. But the market is treating tonight’s release as a verdict on the entire memory trade: confirm the shortage, buy anything with DRAM in it; miss, and tech gets a haircut.
The little detail that actually matters is buried a few lines deeper in the same preview: Q4 DRAM contract prices are expected to rise 10-15% sequentially. Still up. Also a long way from the ~60% jumps of Q2. The shortage is real and profitable. The runaway phase of it may already be behind us.
So the headline isn’t the interesting part. Ignored below by many is the number that actually changes the thesis: Q4 DRAM contract prices are expected to rise 10-15% sequentially. Still up. Also a long way from the ~60% jumps of Q2. The shortage is real and profitable. The runaway phase of it may already be behind us.
That distinction matters more than the record. The easy version of the memory trade runs on commodity inflation: spot prices go vertical, margins follow, buy the sector. The next leg runs on execution, who can shift production into high-bandwidth memory fast enough to hold margins while plain DRAM pricing normalizes. Same sector, completely different trade.
Micron is the cleanest place to watch this play out. The reported financials are strong, an 87% non-GAAP gross margin and record cash generation give it room to fund the HBM transition without flinching. But the tape has started asking the harder question. MU closed near $1,045, down about 2% on the week, and Tuesday’s session faded from its open. The older bullish structure is still standing, but it’s losing momentum.
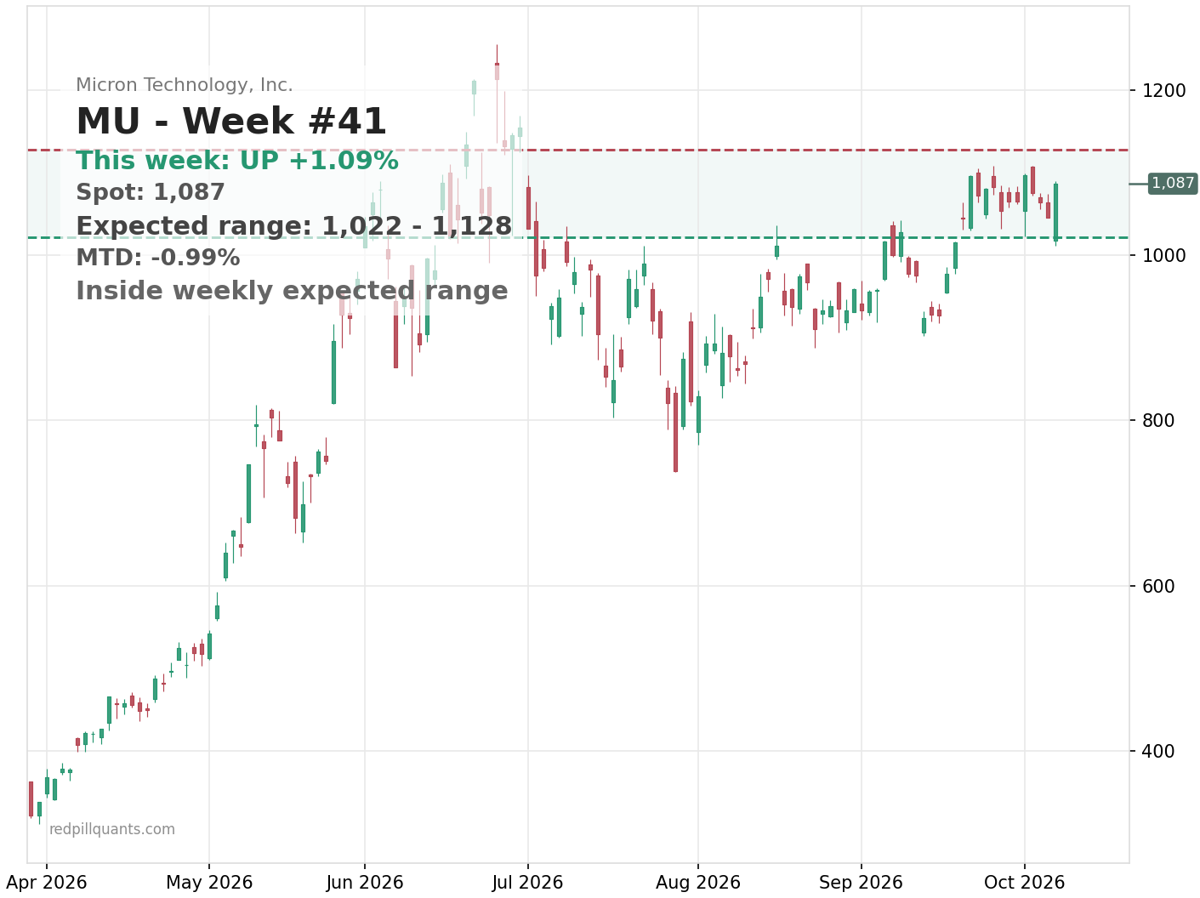
The weekly expected move on MU is narrow, about 5%, so options aren’t pricing a panic in either direction. The market is calm about tonight’s event and quietly less calm about the quarter after it. Those are two different trades wearing the same ticker.
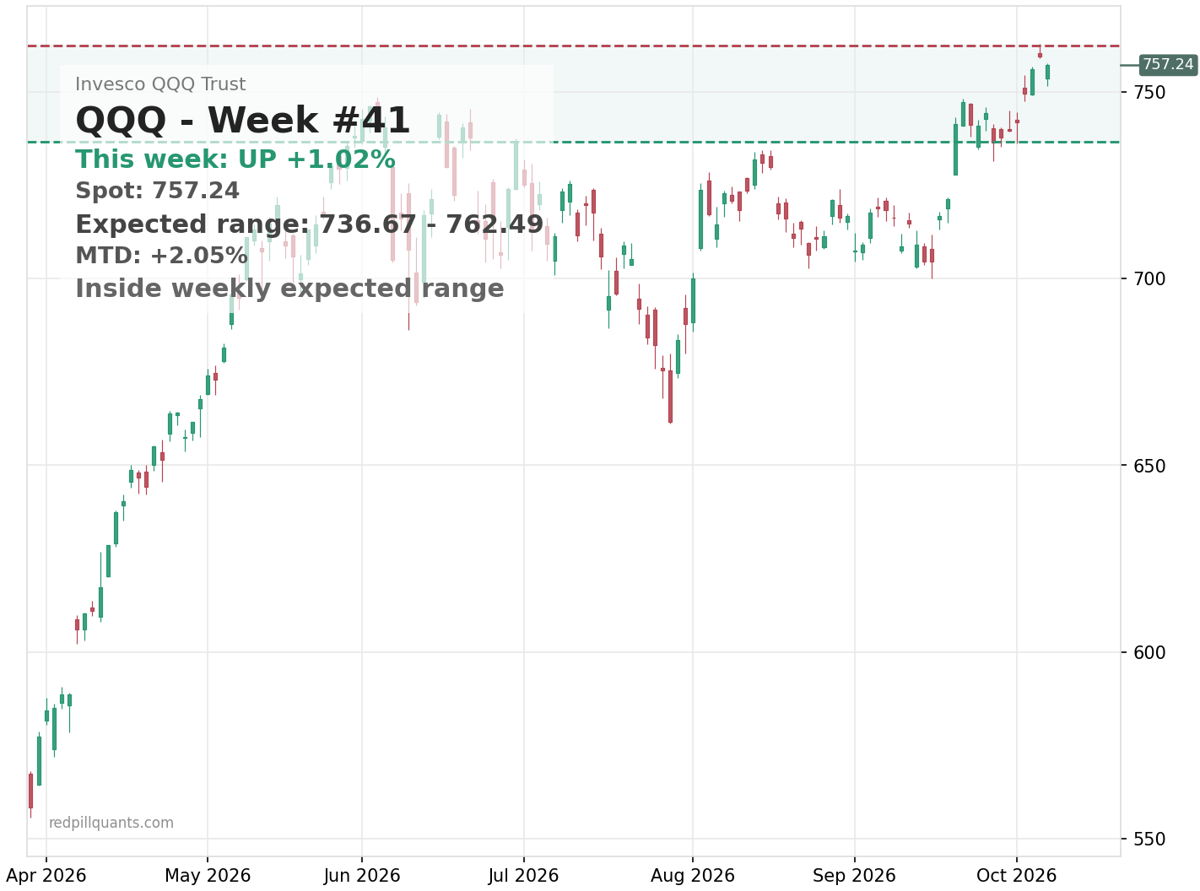
QQQ, meanwhile, is doing its best impression of a market without a care. It closed near $760, a rounding error below its three-month high, with a weekly expected move under 2%. The level being watched below is $755, and the chatter has $748-750 as the next stop if that gives way. A Samsung miss is the obvious candidate to test it. A clean confirmation probably just extends the drift.
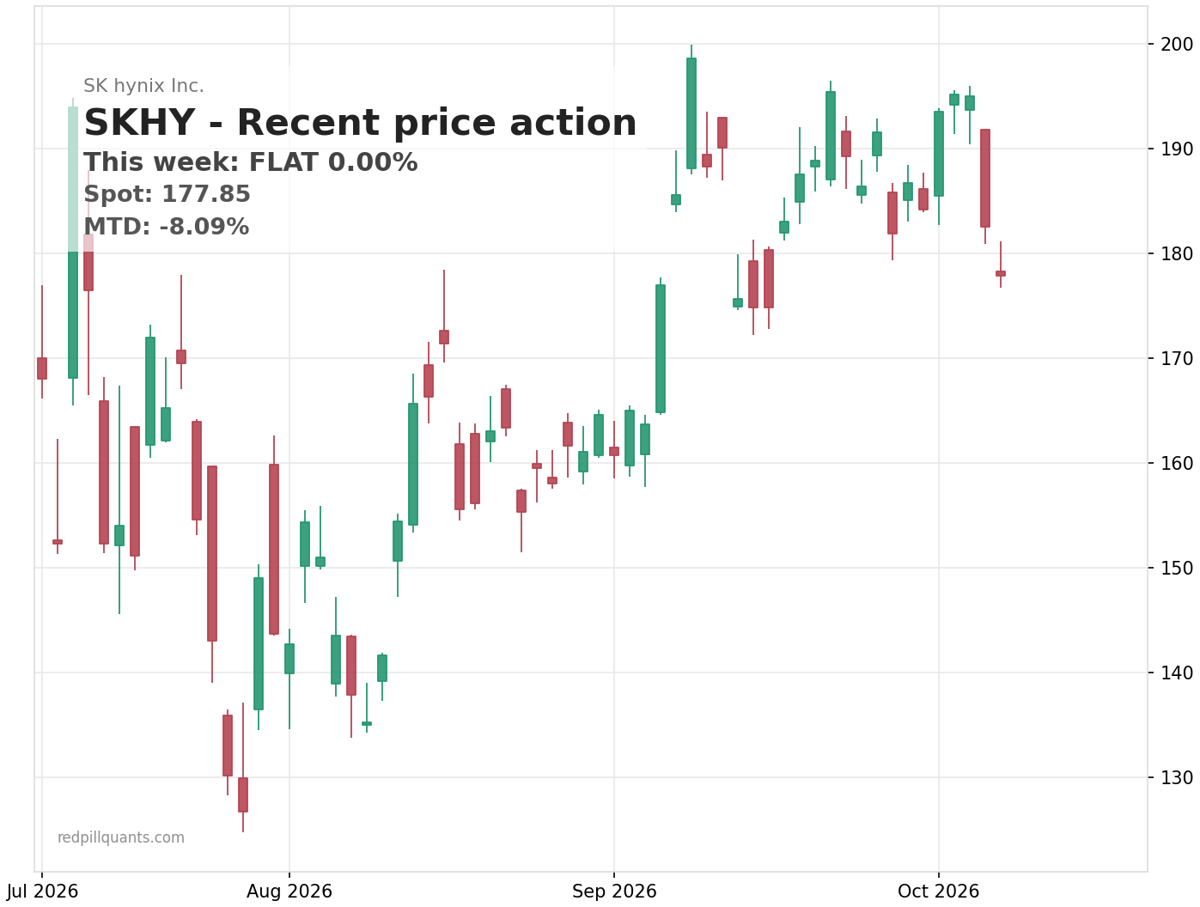
One more tape note before the event: SKHY got hit for over 6% on Tuesday, giving back the prior week’s strength in a single day. The older bullish structure there is under real pressure, and I don’t have expected-move context on it, so size any opinion accordingly.
The mistake tonight is letting a loud headline do your thinking. A record print confirms what the market already believes, and confirmation is the cheapest thing a market can sell you. What the headline won’t tell you is whether the next leg of this trade is commodity inflation or mix-shift execution, and those two stories have very different shelf lives. Watch the Q4 pricing commentary, not the confetti.
If you want this kind of read, structure, trend state, volatility, and what the options market is actually pricing, turned into live signals, that’s what SPY Alpha does for equities and index options. Sign up here.
Cheers,
Michael