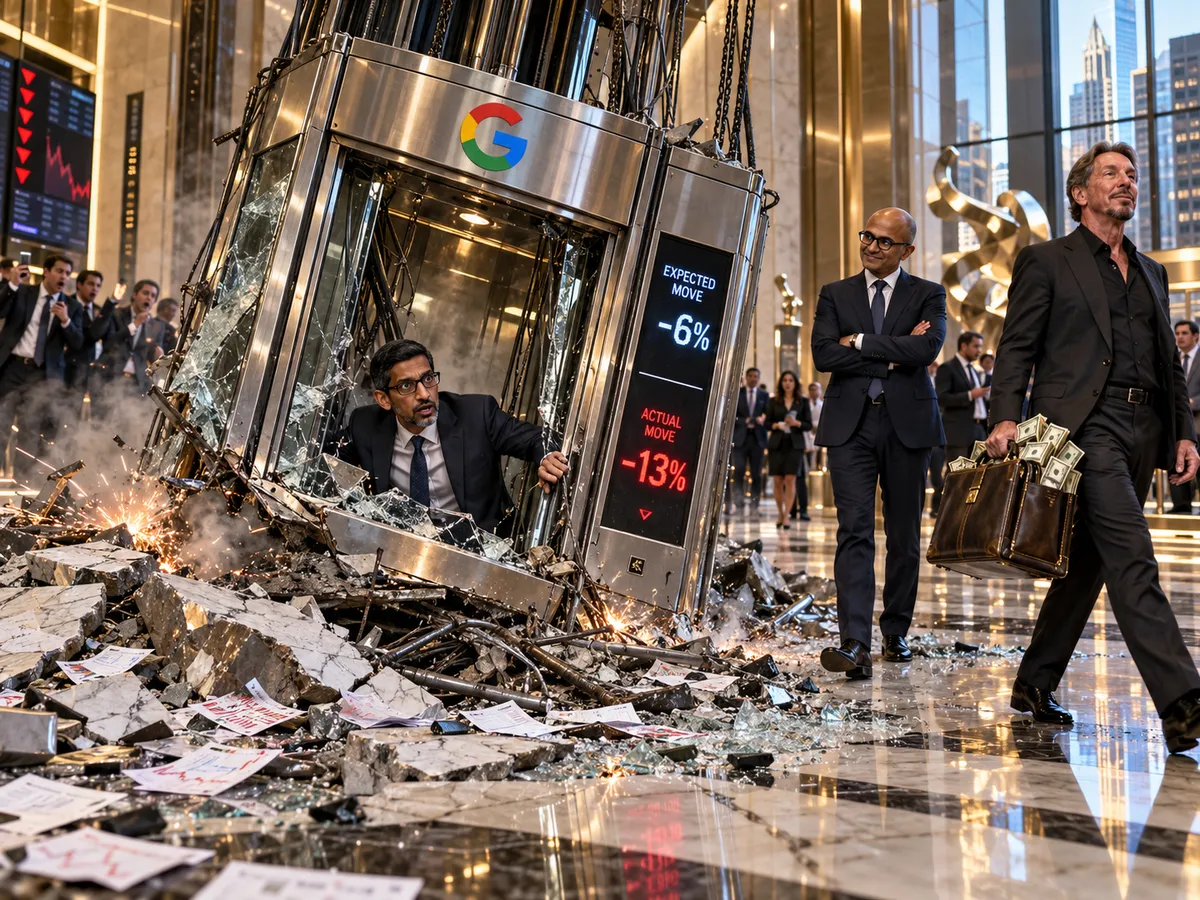
Alphabet doubled cloud revenue and still got almost 13% knocked off the stock in a single session. It closed at $283, about 1% above its three-month low. Anyone who bought it for the cloud story was looking was buying the narrative. The market is deciding on cash flow.
 Desks are calling it the worst earnings reaction since the 2004 IPO. I guess congrats are in order.
Now, here is the mismatch: revenue missed by less than half a percent, and the stock lost almost 13%. You don’t lose that over a rounding error. You lose it over what the miss sat next to.
Free cash flow came in at negative $9.1 billion against a forecast of negative $2.3 billion, the second straight negative quarter. Capex ran $51.4 billion in one quarter, though still about 7% under the Street, so this was a cash generation problem, not a spending surprise. EPS missed too, but that gap is mostly paper losses on equity stakes. Cloud revenue was a sprint. That capex is a mortgage. Sprinting doesn’t pay a mortgage.
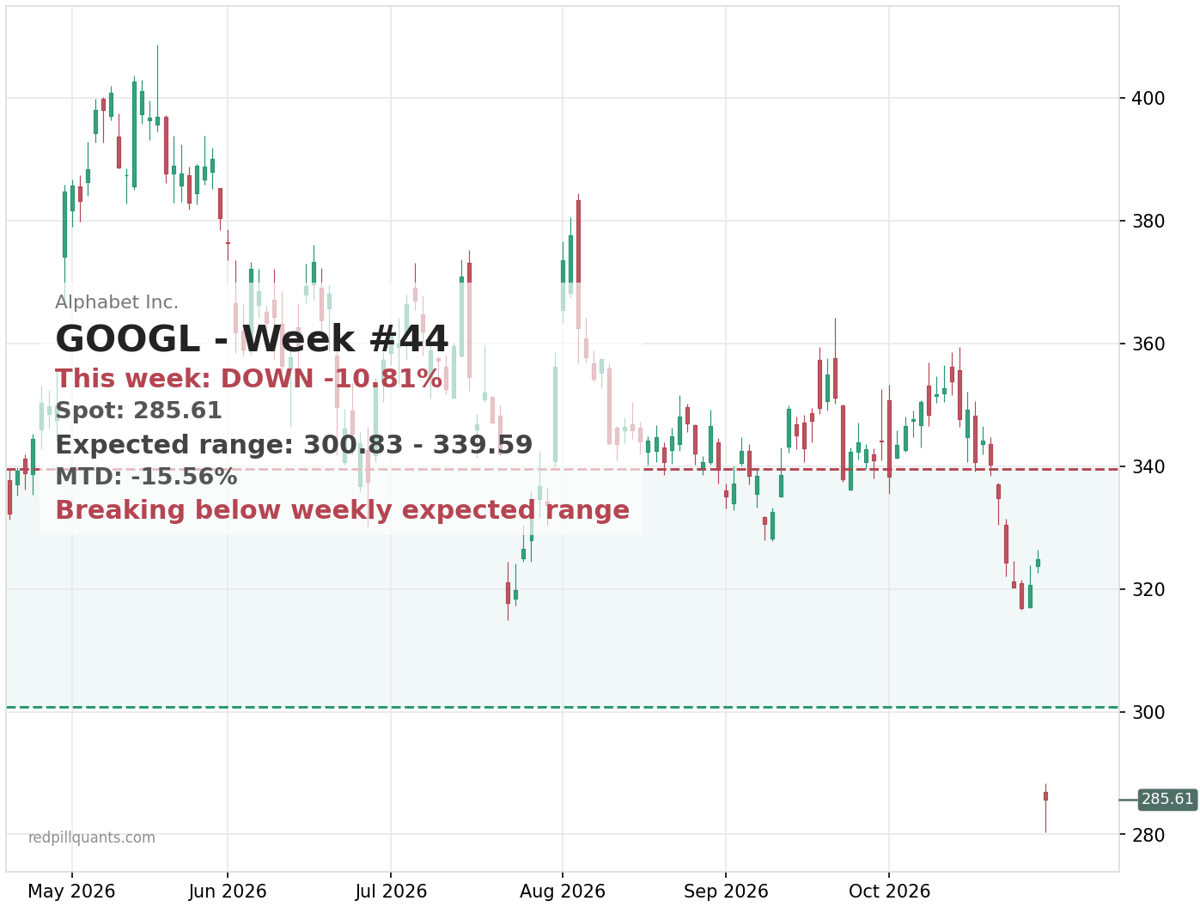
The options market had priced a normal week, with a weekly expected move around 6% and a lower rail near $301. The stock closed through that floor in one session. When a name blows through its expected move on earnings, the pre-earnings pricing inputs are no longer in charge. They are just the numbers you argued about last Thursday.
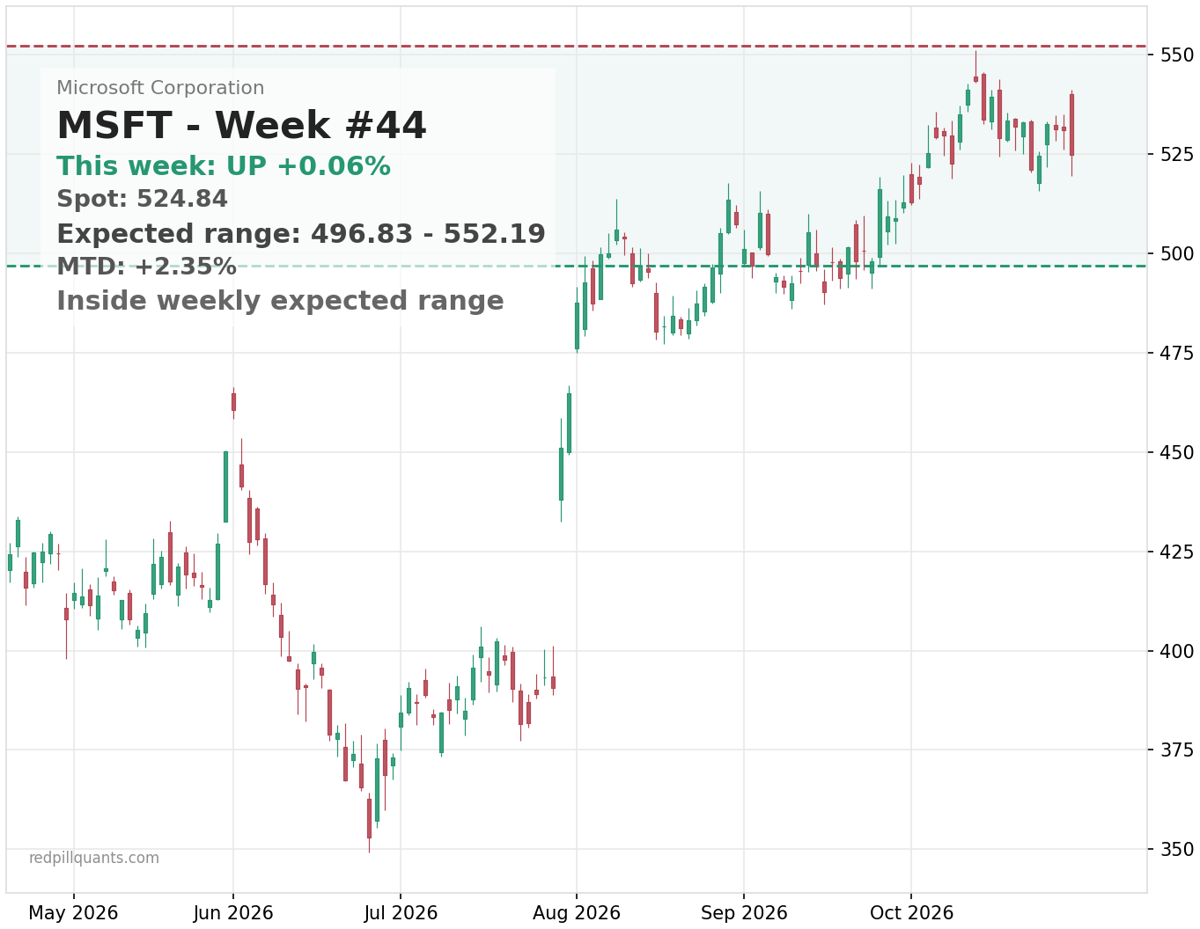 Microsoft is getting credit for Azure growth with capex held under estimates. It sits near the top of its three-month range at $528, inside its expected move, in an uptrend my trend filter has tracked for 66 sessions. Its reward for spending discipline was the unglamorous one: it didn’t get shot. In this tape that counts as a bonus.
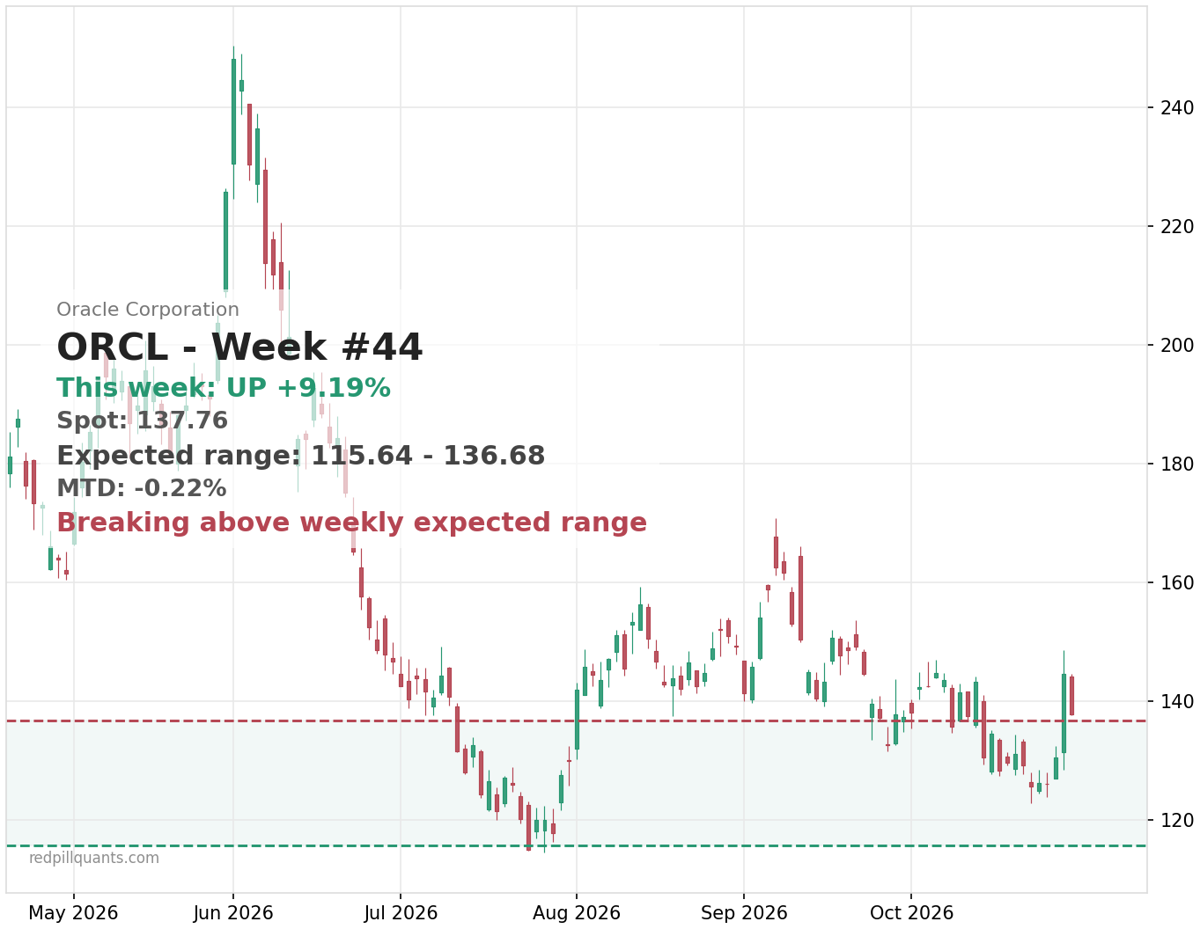 Oracle fits the same pattern. ORCL is up more than 11% on the week at $140 and closed above the upper rail of a wide expected move on long-dated AI commitments tied to OpenAI. The market will still pay for an AI story. It just wants the revenue contracted before the cement gets poured.
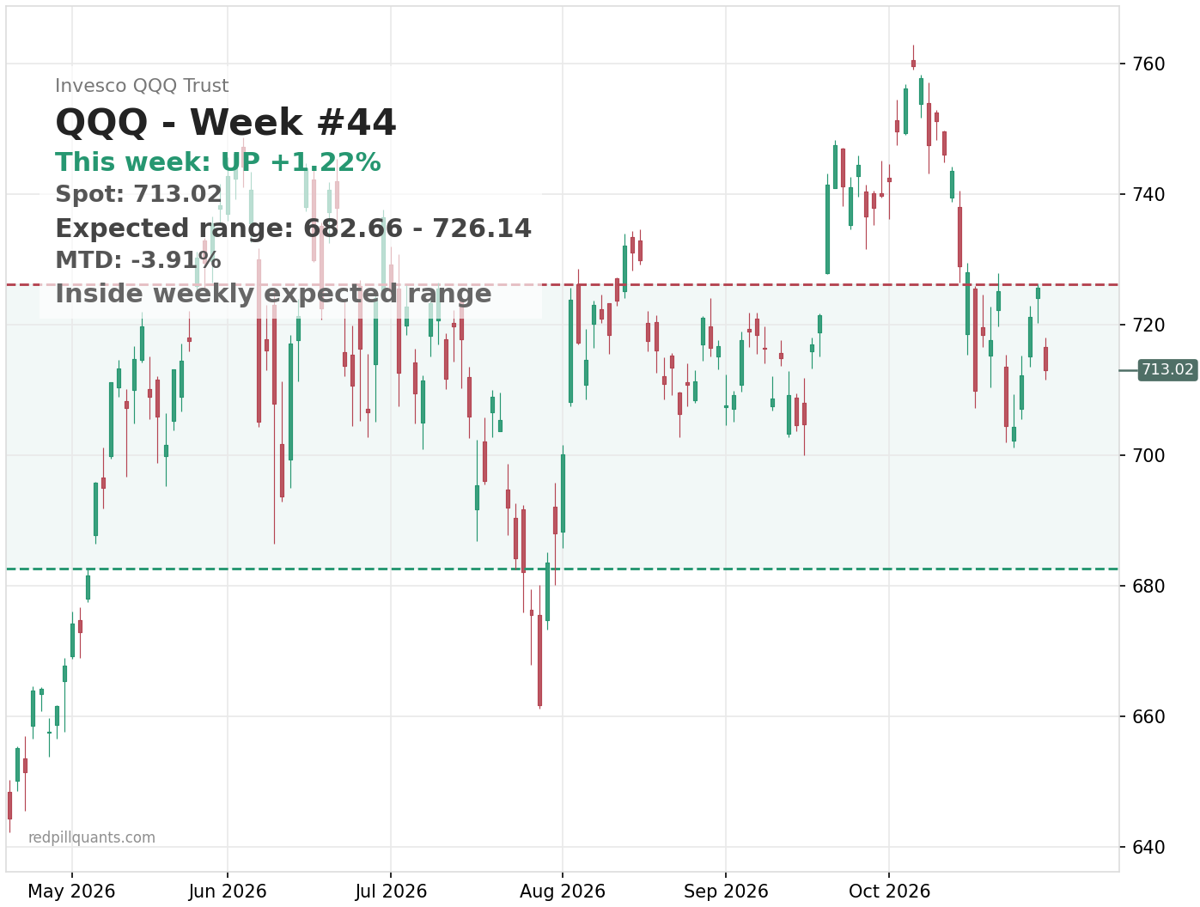 And the index? QQQ eased 1.7% on the day, SPY is flat on the week, and the VIX closed at 17.2. A broad repricing of tech does not look like that. This is one balance sheet getting repriced while everyone else watches.
My working read: this earnings season is re-ranking AI stocks by free cash flow credibility rather than AI exposure. I have been wrong before and I will be wrong again by Friday. The alternatives are not small. The search numbers raise a cannibalization question that belongs to Alphabet alone, and a gap this extreme can be plain overreaction.
On our side, the timing was design, not heroics. Blitzer’s GOOG call debit spread was closed by its scheduled recycle on October 23rd, the week before the print. It had already lost its full debit, which is a real loss, but defined risk means that was the worst case, not a 13% overnight hole.
Payday Friday spent the week being boring. It closed an ETN bull put at target with about 73% of the credit kept, and cut an INTC bull put early with roughly a third kept. Nobody screenshots the trade that just sat there and paid.
What settles it is follow-through. If GOOGL reclaims the $301 area, the overreaction read gets stronger. If it keeps pressing three-month lows, the repricing has legs. Amazon reports tonight after the close, and its cloud and capex numbers are the next place this gets decided.
If you want this kind of read, trend state, expected move, structure fit, turned into live equity and options signals, that is exactly what the Alpha streams do. SPY Alpha covers equities and index options, and you can check it out here.
Cheers,
Michael